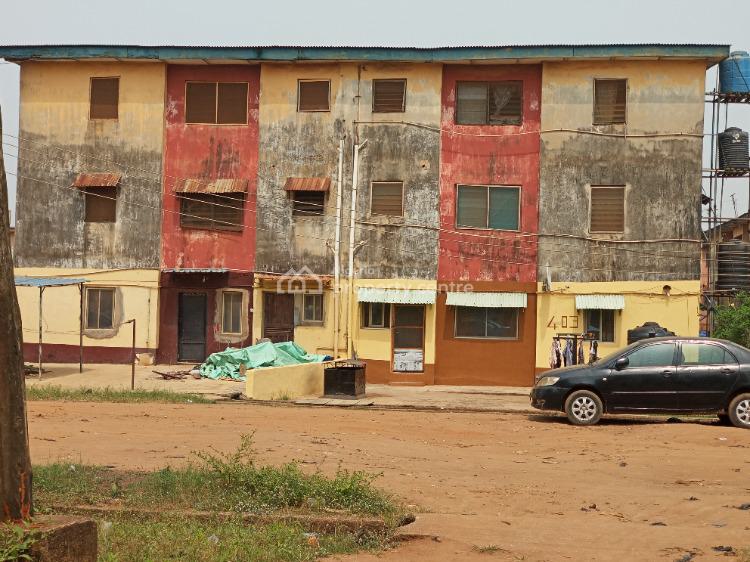

A recent conversation with a friend opened my eyes to an interesting investment dilemma. He purchased an estate apartment building for ₦16 million and rents it out for ₦800,000 annually. While property ownership has its appeal, the numbers tell a compelling story about opportunity cost.
The Math Behind the Investment
With his current rental income, my friend will need 20 years just to break even on his initial investment and that's before accounting for property maintenance, repairs, insurance, and other ownership costs that can significantly eat into returns.
Consider the alternative: if that same ₦16 million had been invested in mutual funds averaging 20% annual returns, the picture looks dramatically different. He would receive approximately ₦3.2 million yearly - That's four times the rental income. Over the same 20-year period, that's ₦64 million in returns without compounding, and potentially much more when you factor in reinvested gains.
Why Mutual Funds Appeal to Me
The advantages of mutual funds in this comparison are clear:
Higher liquidity: Unlike real estate, which can take months to sell, mutual funds can be liquidated relatively quickly when you need access to capital.
Lower maintenance burden: No tenant issues, no roof repairs, no plumbing emergencies at midnight. Your investment works passively while professional fund managers handle the heavy lifting.
Better short to medium-term returns: As the numbers show, the income potential is significantly higher, allowing your money to work harder for you.
Lower entry barriers: You don't need ₦16 million to start. Mutual funds allow you to begin with smaller amounts and scale up over time.
The Wisdom of Diversification
However, here's where nuance matters: while I believe mutual funds offer superior returns in this scenario, putting all your eggs in one basket, whether real estate or mutual funds, isn't the smartest strategy.
Real estate has distinct advantages that shouldn't be dismissed:
- Tangible asset: Property is a physical asset that provides intrinsic value and can serve multiple purposes
- Hedge against inflation: Property values and rental income typically rise with inflation
- Legacy and generational wealth: Real estate can be passed down to children and provides long-term stability
- Forced savings: The illiquidity that seems like a disadvantage also prevents impulsive withdrawals
The ideal approach is to combine both asset classes. Allocate a portion of your portfolio to mutual funds for growth and liquidity, while maintaining some real estate holdings for stability and diversification. This balanced strategy protects you from market volatility in either sector while allowing you to benefit from the strengths of both.
Don't just invest—invest strategically.
IF YOU WANT TO GET MONEY MAKING UPDATES FAST BEFORE OTHERS, CLICK HERE TO JOIN OUR FACEBOOK PAGE